Running a business can get expensive quickly. You might have a business loan, credit card balance, equipment finance, and a few supplier bills all being paid on different dates.
When those payments start eating too much of your monthly income, business debt consolidation can look attractive. One of the biggest questions is whether choosing a longer repayment term can actually make your monthly cash flow easier to manage.
The short answer is yes. A longer term usually means a lower monthly payment. But there’s a cost attached to that lower payment.
How business debt consolidation works
Business debt consolidation means combining several debts into one new borrowing arrangement.
For example, a UK business might have:
- £10,000 on a business credit card
- £15,000 remaining on a business loan
- £5,000 of equipment finance
That’s £30,000 owed across 3 accounts.
A consolidation loan could potentially replace those separate payments with one monthly payment. The exact terms depend on the lender, your business finances, credit history, existing debts, and the type of borrowing you’re applying for.
The main attraction is simple: one payment can be easier to manage than several.
Why a longer term can reduce monthly pressure
Your repayment period has a direct effect on the size of your monthly payment.
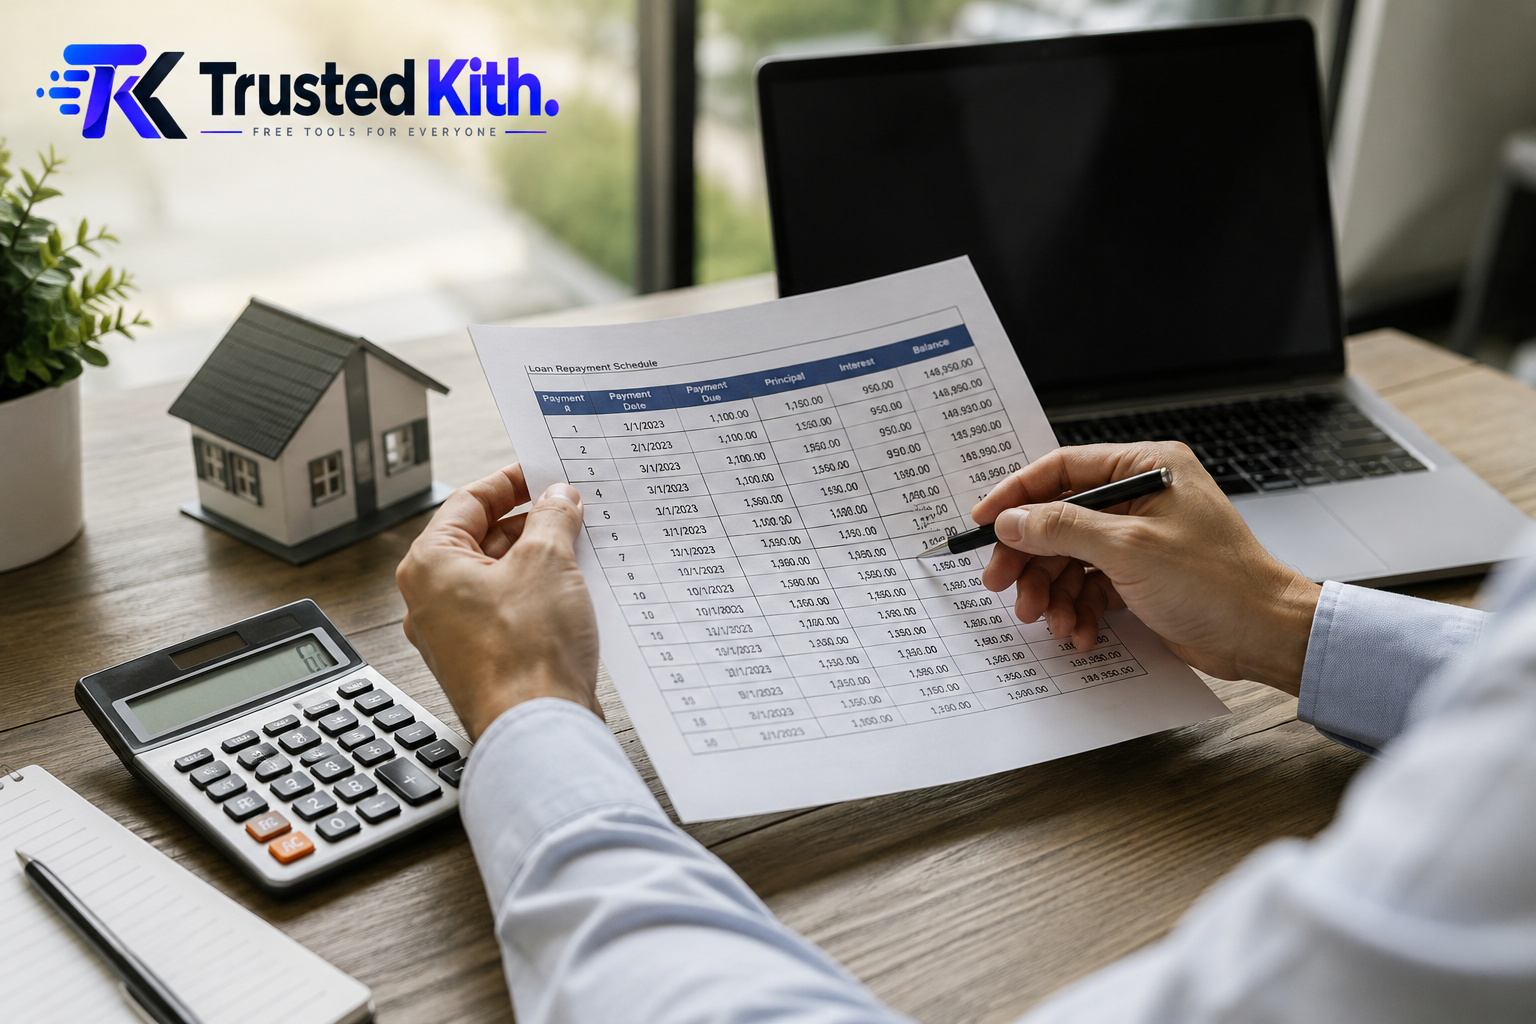
Say you borrow £30,000 and repay it over 3 years. Your monthly payment will generally be higher than if the same amount is spread over 5 years, assuming the interest rate and other costs are comparable.
With a longer term, the balance is spread across more monthly payments.
That can leave more cash in your business bank account each month. For a business dealing with uneven sales, seasonal income, or tight working capital, that breathing room can matter.
A £900 monthly repayment can feel very different from a £600 repayment when you’re already paying staff, rent, suppliers and tax.
Lower payments don’t mean lower borrowing costs
This is where you need to be careful.
A longer repayment period can reduce the monthly payment, but you may pay interest for more months. The total amount paid over the full agreement can therefore be higher.
Consider a simple example.
You borrow £30,000 at the same interest rate and compare a 3-year term with a 5-year term. The 5-year option will usually have a lower monthly payment, but you’ll make payments for an extra 2 years.
So when comparing consolidation offers, don’t look only at the monthly figure.
Check the total amount repayable, interest rate, fees and repayment period.
A payment that looks comfortable today can become expensive over the life of the agreement.
When a longer term can make sense
A longer term can be useful when your main problem is monthly cash flow.
Imagine your business is profitable, but money comes in at different times of the month. You might have strong sales overall while still struggling to cover several large debt payments during quieter weeks.
Reducing the monthly debt commitment can give you more room to cover normal operating costs.
It can also make budgeting easier because you know exactly what needs to leave the business account each month.
For some businesses, that predictability is worth paying more interest over time.
When a longer term may be a poor choice
There are situations where stretching the debt over a longer period can create another problem.
If the business already has weak profits and the debt isn’t being reduced because spending remains too high, lowering the monthly payment won’t fix the underlying issue.
You’ll simply have the debt around for longer.
The same applies if you’re using consolidation to repeatedly borrow more money. Moving balances into one loan doesn’t remove the debt. It changes how you repay it.
Before extending the term, look at why the business needs the extra monthly cash flow in the first place.
Look at your real monthly cash flow
Before applying for consolidation, write down what actually comes in and goes out each month.
Include business income, wages, rent, software, suppliers, tax payments, existing debt repayments and other regular costs.
Then look at what’s left.
If debt repayments are taking a large part of your available cash, a lower monthly consolidation payment could give the business more room to operate.
But if there’s barely any cash left even after removing the debt payments, you may need to look at the wider finances rather than relying on a longer loan term.
Don’t compare loans by monthly payment alone
This is probably the biggest mistake to avoid.
A lender might show you a monthly payment that looks affordable. That’s useful, but it doesn’t tell you the whole story.
When comparing business debt consolidation options in the UK, check:
- Interest rate
- APR where applicable
- Total amount repayable
- Loan term
- Arrangement or application fees
- Early repayment charges
- Whether the rate is fixed or variable
- Whether security or a personal guarantee is required
Read the agreement carefully before committing.
The cheapest-looking monthly payment isn’t automatically the cheapest option.
What about tax and accounting?
Debt consolidation itself doesn’t automatically make business debt disappear for tax purposes.
Interest and finance costs can have accounting and tax implications depending on the structure of the borrowing and how the money is used. Your circumstances matter, so it’s sensible to check the treatment with your accountant before making a major restructuring decision.
Keep records of the old debts, the new agreement and any fees connected with the consolidation.
That paperwork can save headaches later.
A longer term can help cash flow, but there’s a trade-off
If your business is struggling because monthly debt repayments are too high, extending the repayment period can reduce that immediate pressure.
You get a smaller monthly commitment and more cash available for day-to-day expenses.
But you’re potentially paying interest for longer.
So the right question isn’t simply, “Can I get a lower monthly payment?”
Ask yourself:
Does the lower payment give my business enough breathing room to stay healthy, and is the extra total cost reasonable?
If the answer is yes, a longer term may be worth considering.
If the business is losing money every month, though, debt consolidation alone probably won’t solve the problem. You need to understand the cash-flow problem before taking on a new repayment agreement.