Short answer: yes, in most cases. Understanding salary sacrifice Medicare levy calculation Australia rules comes down to one fact: the levy is calculated on your taxable income, and salary sacrifice lowers that number.
But there’s a catch that trips people up, especially with novated leases. Here’s the full picture.
What counts as salary sacrifice in Australia?
Salary sacrifice is an arrangement with your employer where part of your pre-tax salary goes toward a benefit instead of landing in your bank account as cash. Common examples: extra superannuation contributions, a novated lease car, or work-related devices.
Because the sacrificed amount comes out before tax, it reduces your taxable income for the year. That’s the whole appeal.
How the Medicare levy is calculated
The Medicare levy is a flat 2% of your taxable income for most Australian residents, on top of the income tax you already pay. Lower-income earners get a reduction or full exemption below certain thresholds, and these thresholds do shift most financial years, so check the current figures on the ATO site before you rely on them.
The formula is simple:
Medicare levy = Taxable income × 2%
Since salary sacrifice reduces taxable income, it reduces the levy too, in the same proportion.
Salary sacrifice Medicare levy calculation Australia: a worked example
Say your gross salary is $95,000 and you sacrifice $10,000 a year into superannuation.
Without salary sacrifice:
- Taxable income: $95,000
- Medicare levy: $95,000 × 2% = $1,900
With salary sacrifice:
- Taxable income: $85,000
- Medicare levy: $85,000 × 2% = $1,700
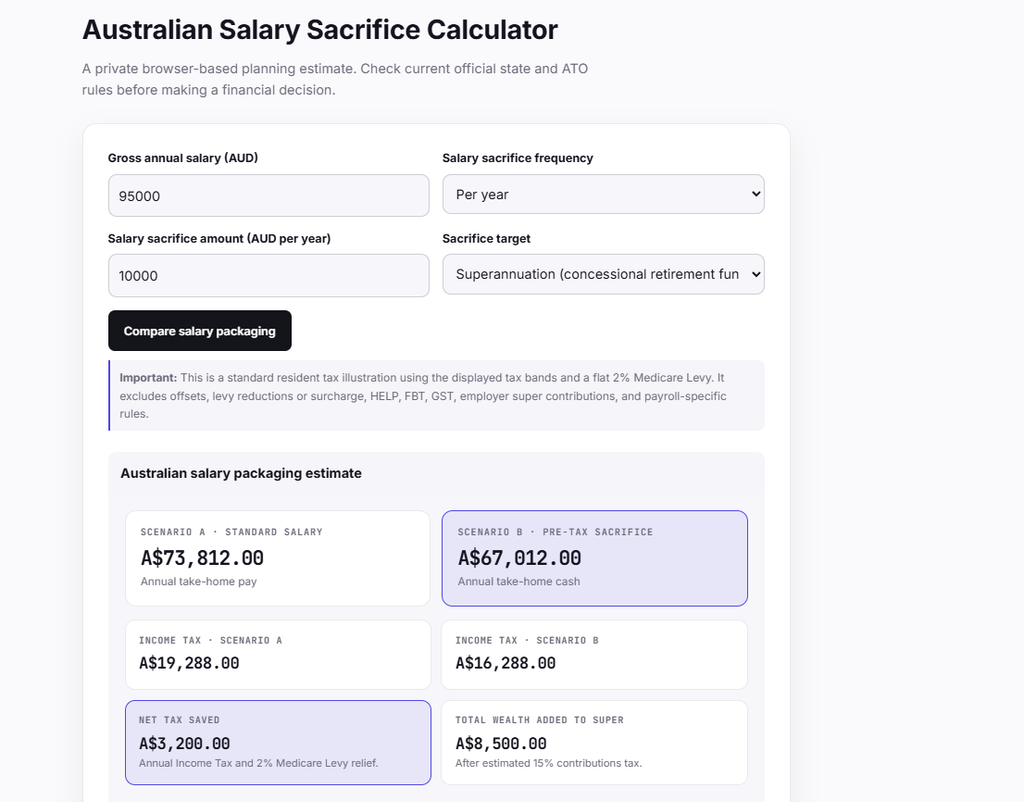
That’s a $200 saving on the Medicare levy alone, separate from whatever you save on income tax by dropping into a lower marginal rate. Sacrifice more, and the levy drops further, proportionally.
The catch: reportable fringe benefits and the Medicare Levy Surcharge
Here’s the part that catches people out. If you salary sacrifice into a novated lease or certain fringe benefits, the arrangement still lowers your taxable income for the standard 2% levy, same as the super example above.
But the ATO also requires your employer to report a “reportable fringe benefits amount” on your income statement. That figure gets added back in when calculating your income for other tests, most importantly the Medicare Levy Surcharge (MLS), which is a separate, additional charge (not the base levy) for higher earners who don’t hold private hospital cover.
So a novated lease can genuinely lower your standard Medicare levy while simultaneously pushing your MLS-assessable income back up closer to where it started. If you’re near an MLS threshold, this matters a lot. If you’re well below it, it usually doesn’t.
The same reportable fringe benefits figure also affects things like HECS-HELP repayment thresholds and family assistance income tests, so it’s worth understanding even outside the Medicare levy question specifically.
Common mistakes people make with this calculation
Mixing up the Medicare levy and the Medicare Levy Surcharge. They’re two different charges with two different rules. Salary sacrifice affects them differently depending on the type of benefit.
Assuming all salary sacrifice works the same way. Super contributions and fringe benefits like novated leases interact with your taxable income and reportable income differently.
Forgetting the low-income thresholds change yearly. If you’re near the exemption or reduction threshold, always check the current year’s figures rather than reusing an old number.
Not accounting for the surcharge separately. A saving on the base levy doesn’t automatically mean a saving on the surcharge, if it applies to you.
Check your own numbers
Every income situation is different, and thresholds shift year to year, so running your actual salary and sacrifice amount through a calculator beats guessing. Browse the free Australian Salary Sacrifice Calculator on this site to check your own numbers before making a decision.
For the current official rates and thresholds, the ATO’s Medicare levy page is the source to check directly.
FAQ
Does salary sacrificing to super always reduce my Medicare levy? Yes, since it reduces your taxable income, and the levy is calculated as a straight percentage of that income.
Does a novated lease reduce my Medicare levy the same way? It reduces the standard 2% levy the same way, but the reportable fringe benefit gets added back for other tests like the Medicare Levy Surcharge.
What’s the difference between the Medicare levy and the Medicare Levy Surcharge? The levy is a standard 2% most residents pay. The surcharge is an extra charge, roughly 1% to 1.5%, for higher earners without private hospital cover.
Can salary sacrifice bring me below the Medicare levy threshold entirely? It’s possible if you’re already close to the low-income threshold, since sacrificing enough could drop your taxable income into the reduced or exempt range.
Do I need to declare salary sacrifice amounts myself at tax time? No, your employer reports the sacrificed super and any reportable fringe benefits on your income statement, and the ATO applies these automatically to the relevant calculations.